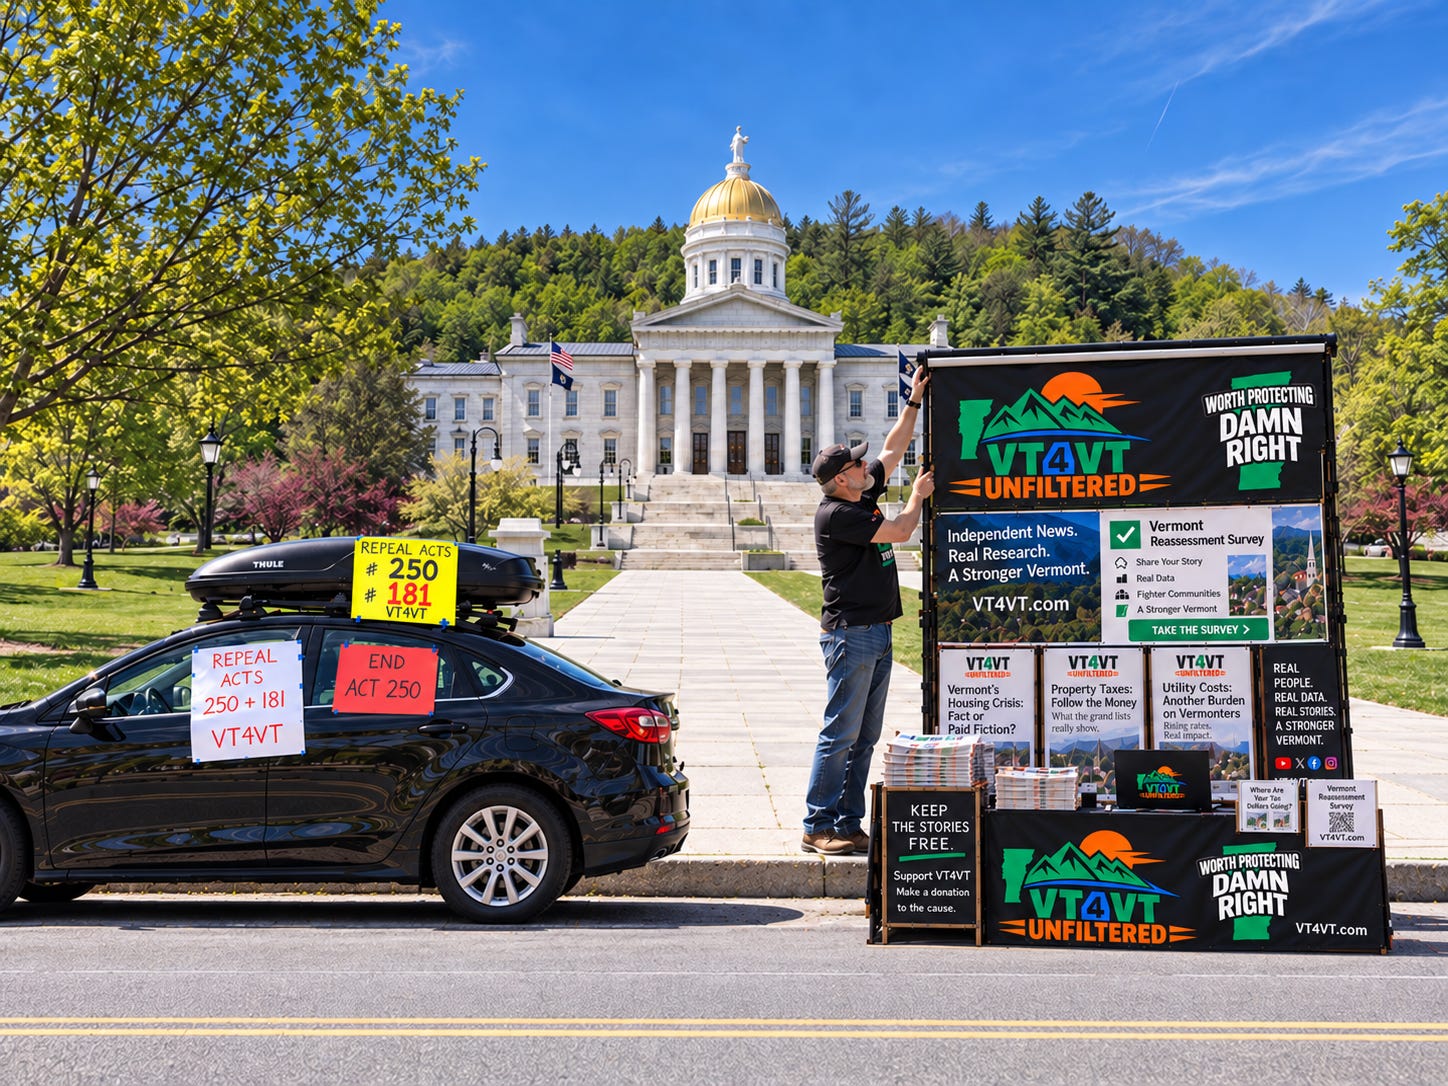
On May 21, 2026, I published The Coming Property Tax Collapse in Vermont — A State in Emergency. VT4VT was barely getting started. We did not have much then beyond a couple of signs, my Chevy Volt, a few days standing at the State House, some early posts on Rural Vermont Rising, and maybe the beginnings of a YouTube channel. We certainly did not have a library of municipal grand lists, a statewide reassessment survey, or months of property-tax research behind us. We had not yet launched the VT4VT website, and social media, the vt4vt.substack.com, or the Vermont Reassessment Survey, and we had not worked through New Haven, Colchester, Stockbridge or the other town records that would eventually change the way we looked at Vermont property taxes.
What we had were reassessment notices showing values doubling, tripling and in some cases rising even more, along with a December education-property-tax forecast from the Vermont Department of Taxes that was difficult to ignore. Tax Commissioner Bill Shouldice had projected that the average education-property-tax bill could rise another 11.9 percent in FY2027 and said that, if the increase took effect, education property taxes would have risen nearly 41 percent over five years.
Looking at those two things together in May, the concern seemed straightforward. Vermont was moving into a new reappraisal system while homeowners in the first towns were receiving enormous increases in assessed value, and the state was simultaneously projecting another substantial increase in education-property-tax bills.
What happens when those two things meet?
That was the question behind the May article.
Five months later, we have a much better answer.
Where We Were in May
One of the things we did not fully understand in May was that Vermont was not about to reassess every property in the state at the same time. The statewide change was the reappraisal requirement itself. Under Act 68, municipalities are now generally required to complete a full reappraisal every six years unless Property Valuation and Review approves a longer period. The requirement took effect January 1, 2025, but towns move through the process on their own schedules.
Roughly 40 Vermont communities completed town wide reassessments in this first group. We documented that number ourselves in September when VT4VT published Vermont’s Reassessment Numbers Are In. We Need Your Help. At that point, more than 91 Vermonters had completed the reassessment survey, but those responses represented only a fraction of the properties affected in those roughly 40 municipalities.
The rest of Vermont is still coming.
That is an important correction to some of our earlier language. Vermont has established a statewide recurring reappraisal system, but Vermont has not completed one simultaneous statewide reassessment. The towns that went through the process in 2026 are the first substantial group in a cycle that will continue through this tax year and the years ahead.
There was another piece we did not fully appreciate in May. We were looking at the Common Level of Appraisal, the education-property-tax forecast and the extraordinary assessment increases appearing in the first reappraisal towns, but we had not yet seen how Vermont would ultimately treat those newly reappraised towns when the final FY2027 rates were calculated.
The Legislature clarified that during the 2026 session. Act 164, effective June 18, provides that a municipality completing a reappraisal has its CLA set at 100 percent for that year. The Department of Taxes’ final FY2027 rate table then identifies the towns completing 2026 reappraisals and incorporates that treatment into their education-property-tax calculations.
That was not how we were looking at the problem on May 21.
We saw properties doubling or tripling in assessed value and a state education-tax system already under enormous pressure. We did not yet have the final rates showing how those new grand lists would interact with the education-tax calculation.
Once those rates arrived, the picture became clearer.
It did not become inexpensive.
Then We Started Digging
The May article did not end the inquiry. It started it.
On June 5, VT4VT published Vermont’s Rural Cost of Reassessment, looking more closely at what market-value reassessment can mean in rural communities where a relatively small number of sales can influence values across properties that have not changed hands in decades. Three days later, on June 8, we formally published the Vermont Reassessment Survey. On June 13, Understanding Your Vermont Property Tax tried to explain how assessment and tax rates actually came together on a property-tax bill. By June 27, Addison’s new grand list gave us another municipal example, with total assessed property value increasing by nearly 85 percent.
The work continued in July with Act 68: Just What Vermont Needed During an Affordability Crisis, when we went back into the legislation itself and examined the statutory changes governing Vermont reappraisals. By then, we were no longer looking only at individual notices. We were trying to understand why towns were reassessing, how frequently they would have to do it, what authority Property Valuation and Review had acquired, and how the new system fit into the broader education-property-tax structure.
The September grand-list work moved the investigation again. Once we had complete municipal records instead of isolated examples, we could stop asking what one reassessment notice appeared to mean and start asking what had actually happened across an entire town.
That was when the story became much more interesting.
New Haven Showed Us the Problem Was Not the Percentage Alone
New Haven became the first complete VT4VT public-record case study.
The town’s homestead grand list increased from approximately $208 million in 2024 to approximately $475 million in 2026, an increase of roughly 128 percent. Individual parcels did not rise uniformly. Some increased much more than the town wide average, while others increased less.
At first, the obvious headline was the size of those assessment increases. As we kept working through the records, however, another issue became more significant.
A town wide reappraisal changes more than the number printed on an individual assessment notice. It changes the relationship between that parcel and every other parcel in the town.
Consider a town where the overall grand list doubles. A property that also doubles has roughly maintained its position relative to the town as a whole. A property that rises only 60 percent may represent a smaller share of the new tax base, while one that rises 160 percent may represent a larger share. The tax rate can decline substantially after reassessment and those taxpayers can still experience very different outcomes.
That was a much more useful way to look at what was happening.
It also meant that the dramatic percentage increases coming through the survey could not, by themselves, tell us what happened to property taxes.
We needed the grand lists and the rates.
Colchester Put the Pieces Together
Colchester gave us the clearest demonstration of why.
The town’s 2025 grand list contained approximately $2.299 billion in real-property value. Following the 2026 reappraisal, that value increased to approximately $4.774 billion, a rise of about $2.475 billion, or 107.7 percent.
If we had stopped there, we could easily have described Colchester as a town where property values doubled.
The rates told another part of the story.
Colchester’s municipal rate fell from 0.6745 to 0.3734, a decline of about 44.6 percent. The homestead education rate fell from 1.7384 to 1.1302, while the non-homestead education rate fell from 1.8668 to 1.1555.
Those reductions were substantial, but they did not erase the increase in the amount of property tax being generated.
Our analysis of the published records found state education property taxes increasing from approximately $41.1 million to approximately $50.5 million, an increase of about $9.3 million, or 23 percent. Municipal property taxes increased from approximately $15.4 million to approximately $16.5 million. Combined, the modeled taxes generated increased from roughly $56.5 million to $67 million, about $10.4 million more than the year before.
That was the calculation we had been missing in May.
The assessment could double without the bill doubling because the tax rate fell. But the fact that the rate fell did not mean the tax burden fell with it.
Both numbers had to be examined together.
Colchester also showed why a town wide average could hide what was happening underneath it. While the overall grand list increased approximately 108 percent, some individual parcels increased dramatically while others actually declined in assessed value.
By September, we were no longer trying to answer whether assessments were rising.
We knew they were.
We were trying to determine where the tax burden moved after they did.
Stockbridge Showed Us That Every Town Could Tell a Different Story
Stockbridge made the analysis more complicated again.
The town’s real-property value remained remarkably stable for several years. Its June 2022 grand list reported approximately $124.8 million in real property. The 2024 list was about $126.5 million, and the 2025 billed grand list stood at approximately $126.1 million.
Then came the 2026 reassessment.
VT4VT’s analysis of the reassessed values and tax bills found approximately $244.4 million in assessed real property, an increase of about 93.8 percent in a single reappraisal. Among 742 parcels that could be directly matched between the old and new records, the median increase was approximately 91 percent.
Again, the tax rates fell sharply. Stockbridge’s homestead education rate declined approximately 47.4 percent and its non-homestead education rate declined approximately 47.8 percent. The combined homestead and non-homestead rates also fell.
Even so, the total levy represented by the records increased by approximately $732,000, or 21.7 percent.
The larger surprise was where the increase occurred.
In Colchester, most of the additional property-tax dollars came from the education side. In Stockbridge, approximately 87.5 percent of the increase came from municipal taxation and only about 12.5 percent from education property taxes.
There was no single statewide explanation we could simply repeat from town to town.
The assessment mattered, but so did the municipal budget, the education rate, the distribution of the grand list, the type of property and what had happened to that property relative to everything around it.
That is why the town-by-town work became necessary.
The Grand Lists Also Took Us Beyond Homeowners
The original May article was primarily concerned with homeowners, farms, retirees and rental property.
The grand lists widened that inquiry.
In Colchester, VT4VT identified aggregate Green Mountain Power assessments increasing from approximately $37.9 million to $59.7 million. Vermont Gas increased from approximately $20.9 million to $35.6 million, while VELCO increased from approximately $9.8 million to approximately $18 million.
Stockbridge produced another striking example. Green Mountain Power’s identifiable real-property assessments increased from approximately $2.99 million in 2025 to approximately $8.09 million in 2026, an increase of about 171 percent.
That work led to A Disturbing Trend Is Emerging in Vermont’s Grand Lists, published September 15. The article expanded the investigation beyond homes to utilities, commercial properties and communications infrastructure.
There is a limit to what the grand lists prove. A utility assessment increasing by millions of dollars does not establish that the same amount will simply be added to customers’ bills. Regulated utility costs move through a separate rate-setting process and need to be followed through regulatory filings before we can determine the eventual ratepayer effect.
But the records established something we had not been looking for in May: Vermont’s reappraisal cycle affects much more than residential property.
The Survey Had a Different Job
The Vermont Reassessment Survey also taught us something about evidence.
When we launched it on June 8, the purpose was to find out what Vermonters were experiencing. Reports began coming in from communities around the state, including assessments reported at 100 percent or more above prior values and some far higher.
Those reports gave us leads.
They did not give us completed town analyses.
By September, VT4VT had received more than 91 anonymous reassessment surveys, but roughly 40 towns had gone through reassessment. Ninety-one reports could not describe what happened to every parcel across those communities, much less what will happen as the remaining Vermont municipalities move through their own reappraisals.
That is why the survey and grand-list projects now work together.
The survey identifies what taxpayers are reporting. Municipal records allow us to determine whether those reports fit a broader pattern, how the entire grand list changed and what happened when the final tax rates were applied.
Neither replaces the other.
What We Got Wrong in May
Looking back at the May article, some of the language went farther than the evidence available at the time could support.
We said that most rural Vermonters would not survive financially if the trend continued. We did not have enough evidence to establish that. We said that if property taxes doubled or tripled, rents would follow because “that is just math.” Higher property taxes are an operating cost for rental property, but rental markets are influenced by supply, demand, vacancy, financing, maintenance, leases and other expenses as well. The relationship is not mechanically one-for-one.
We also attributed much of Vermont’s valuation increase to post-COVID cash buyers and outside wealth. That remains a legitimate subject for investigation, particularly in rural communities where a small number of sales can influence comparable values, but it requires deed transfers, sales histories and buyer data before it can be established statewide.
The largest misunderstanding, however, concerned the interaction between reassessment and the tax rate.
In May, we were looking at properties doubling and tripling in value while the state was projecting another substantial education-property-tax increase. We did not yet have the final FY2027 rates or a full understanding of how the first reappraisal towns would be treated after their new grand lists were completed.
Today we do.
The Legislature set a completed reappraisal town’s CLA at 100 percent for that year, and the final education-property-tax tables identify those towns separately. The first group of approximately 40 municipalities therefore gives us an early look at how the new system behaves rather than a completed statewide result.
That correction does not erase the affordability problem.
It tells us where to measure it.
What the Records Have Shown So Far
Five months of research have produced a much clearer picture than we had in May.
Large reassessment increases are real. New Haven, Colchester, Stockbridge and other municipal records document them directly. They are not simply anonymous reports from worried property owners. Large assessment increases do not automatically produce equally large tax increases. Colchester and Stockbridge both demonstrated how sharply tax rates can fall after a major reappraisal. Lower rates do not automatically mean lower taxes, either. In both Colchester and Stockbridge, the records showed more property-tax dollars being generated after reassessment despite significant rate reductions.
The source of those increases can differ sharply from one municipality to another. Colchester’s increase was concentrated heavily on the education side, while Stockbridge’s was overwhelmingly municipal.
Reassessment can redistribute the tax burden even when the total levy changes only modestly because individual parcels do not move uniformly with the town wide grand list.
And the effect reaches beyond owner-occupied homes. Utilities, commercial property, rental property, camps, farms and land all have to be examined if we want to understand how the tax base is changing.
Those findings are considerably more useful than declaring that every assessment increase will become the same percentage increase on a tax bill.
VT4VT Has Changed Along With the Investigation
There is another part of this story worth documenting.
In May, VT4VT was essentially one person looking at a property-tax bill and trying to understand why the numbers no longer made sense.
By June, we had a reassessment survey and were writing about the effect of market-value appraisal on rural property. By July, we were digging through Act 68 and the statutory structure behind the reappraisal system. By September, we were collecting multiple years of municipal grand lists, matching individual parcels, comparing tax rates and calculating actual changes in tax burdens.
The work then expanded into utilities, commercial property, housing policy, property classifications and the history of Vermont’s education-property-tax system. Our September Follow the Property Tax investigation brought many of those strands together, separating Act 68’s reappraisal system from the property-classification changes that had also entered Vermont law.
The project is no longer based on proving the headline we wrote in May.
It is based on building the record.
That is the standard we should be held to.
And Most of Vermont Is Still Ahead of Us
The roughly 40 municipalities that have already gone through this process are not the end of the Vermont reassessment story. They are the beginning.
Act 68 established the six-year recurring requirement for municipalities across the state. Vermont law has continued to evolve since then, including the 100-percent CLA treatment for newly reappraised towns and future plans for Regional Assessment Districts. Under the Department of Taxes’ current guidance, towns remain on individual reappraisal schedules during this first cycle, with additional regional changes contemplated later.
That means we should be careful about declaring a statewide result based on the first group of municipalities.
It also means Vermont has an opportunity it did not have before.
We now know what records to collect before the next towns come through.
We know that the old grand list matters as much as the new one. We know that the final rate matters as much as the reassessment notice. We know that town wide averages can conceal substantial redistribution between individual properties. We know to look at utilities, commercial property and other classes as well as homes. And we know that the final tax bill is where all of those pieces finally meet.
The next towns do not have to begin from scratch.
Neither does VT4VT.
Five Months Later
The May article asked whether Vermont was heading toward a property-tax emergency.
Five months later, I would frame the question differently.
Vermont has already experienced substantial education-property-tax increases, and the Tax Commissioner warned in December that another 11.9 percent statewide-average increase would bring the five-year increase to nearly 41 percent. At the same time, the first major group of municipalities moving through Vermont’s new recurring reappraisal system has produced grand-list increases approaching or exceeding 100 percent in several of the towns we have examined.
What we have learned is that those two numbers do not simply multiply together.
The real outcome is determined town by town and property by property, after new assessments, municipal spending, education rates and the tax calculation all come together.
New Haven showed us how dramatically a grand list can change. Colchester showed us how a grand list can double, rates can fall and the overall tax burden can still increase. Stockbridge showed us that two towns with similar reassessment stories can have very different reasons for their tax increases. The utility analysis showed us that these changes can move beyond homeowners and into other parts of Vermont’s economy.
That is where the investigation stands today.
The May article was the warning.
Everything since then has been the work of finding out what was actually happening.
And with most Vermont municipalities still moving toward their turn in the reappraisal cycle, this investigation is nowhere near finished.
Help Build the FY2027 Record
VT4VT is building an independent database of Vermont grand lists, reassessments, tax rates, final tax bills and municipal records. Vermonters can help by completing the anonymous Vermont Reassessment Survey, submitting their municipality’s complete grand list or a link to it, and sharing reassessment notices and final property-tax information.
Survey responses remain anonymous and are used to identify trends and communities requiring additional research. Public-record findings are reported separately and are based on municipal grand lists, tax-rate documents, legislation, Department of Taxes publications and other official records.
Read the continuing investigation, property-tax tools and town reports at VT4VT.com.
Worth Protecting.
Damn Right.
VT4VT Research Trail
The Coming Property Tax Collapse in Vermont — A State in Emergency
May 21, 2026
VT4VT Substack Archive
Vermont’s Rural Cost of Reassessment
June 5, 2026
VT4VT Substack Archive
Vermont Reassessment Survey
June 8, 2026
Vermont Reassessment Survey article
Understanding Your Vermont Property Tax
June 13, 2026
VT4VT Substack Archive
The Origin Story for VT4VT
June 21, 2026
The Origin Story for VT4VT
Addison’s Grand List Is Out, and the Numbers Are Hard to Ignore
June 27, 2026
VT4VT Substack Archive
Act 68: Just What Vermont Needed During an Affordability Crisis
July 9, 2026
Act 68 article
Colchester Reassessment: The Grand List More Than Doubled. What Happened to Property Taxes, Utilities?
September 1, 2026
Colchester Reassessment Report
Vermont’s Reassessment Numbers Are In. We Need Your Help.
September 2, 2026
Vermont’s Reassessment Numbers Are In
Stockbridge’s 2026 Assessments Nearly Doubled
September 14, 2026
Stockbridge Reassessment Report
A Disturbing Trend Is Emerging in Vermont’s Grand Lists
September 15, 2026
Utility and Commercial Grand List Analysis
I Am Not a Charity or a Blank Check
September 17, 2026
I Am Not a Charity or a Blank Check
Vermont’s Housing Crisis: Fact or Paid Fiction? — Follow the Property Tax
September 22, 2026
Follow the Property Tax
Primary Public Records and Official Sources
Vermont Department of Taxes — Reappraisals
Reappraisals and six-year requirement
Vermont Department of Taxes — 2026 Reappraisal Status by Town
2026 Reappraisal Status by Town
Vermont Department of Taxes — FY2027 Education Property Tax Rates
FY2027 Education Property Tax Rates
Vermont Department of Taxes — FY2027 Education Tax Rate Letter, December 1, 2025
FY2027 Education Tax Rate Letter
Vermont Department of Taxes — 2026 Legislative Highlights
Includes Act 164, the 100-percent CLA treatment for municipalities completing reappraisal, and Act 169, which established the FY2027 education-property-tax parameters.
2026 Legislative Highlights
Vermont Department of Taxes — Education Tax Rate Calculations
Education Tax Rate FAQ
Vermont Department of Taxes — Listers and Assessors
Listers and Assessors resources
Related VT4VT Research
VT4VT — Vermont Property Tax Research, Grand List Analysis, Reassessments and Public Policy
https://VT4VT.com
Vermont Property Tax Affordability Survey
https://survey.vt4vt.com/s/004-property-tax-affordabiltiy/
Is Vermont Affordable? — Focus on Education
https://survey.vt4vt.com/s/is-vermont-affordable-focus-on-education/
Vermonters can also submit municipal grand lists, reassessment notices, tax bills and other public records to VT4VT to help expand the independent statewide database documenting Vermont property taxes, reassessments and public policy.
Support VT4VT
VT4VT is a program of Fort Aldrich Incorporated, a registered 501(c)(3) nonprofit organization. Contributions supporting VT4VT research, public-record analysis, data tools and civic education may be made through:
VT4VT on Substack
Website: https://VT4VT.com
YouTube: https://www.youtube.com/@Vt4vermont
Instagram: https://www.instagram.com/vt4vermont
TikTok: https://www.tiktok.com/@vt4vt
Quora: https://vermonteesforvermontvt4vt.quora.com/
Threads: https://www.threads.com/@vt4vermont